Caroline Tran: We started the business because we just want people to be clever with their money. Cashback is more of gain rather than discount. It's more of a less loss. Right. So what it means is that if you're an Australian merchant that's selling in the us, we can settle, we can collect in the US and settle into your Australian bank account. We enable growth under the payment staff as well through loyalty. Welcome to add to cart, Australia's leading e commerce podcast that Express delivers all you need to know in the fast moving world of online retail. Here's your host, Bushy.
[Voiceover]: Hey, it's Nathan Bush or Bushy joining you from the land of the terrible people here in Brisbane, Australia.
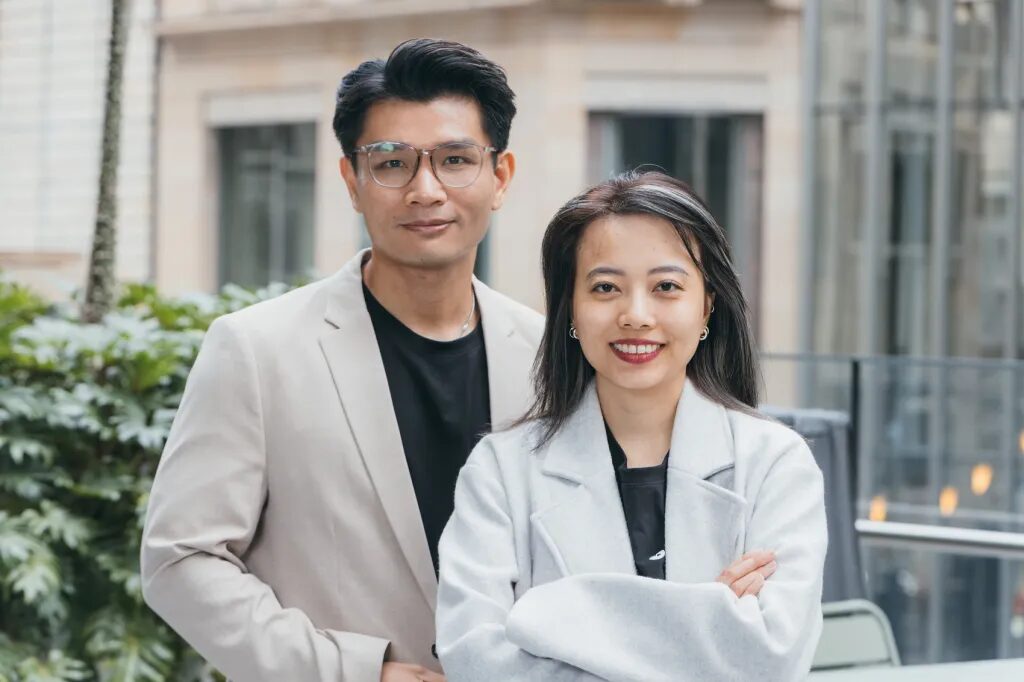
Nathan Bush: Do we have a treat for you today. Today we have one of the hottest startups in Australia. They've raised millions in startup capital and are now expanding into into the U.S. japan and Singapore. And they're a payments company. Joining me today is Carolyn Tran from hello Clever. It's probably the best name for a finance company that you've ever heard of and her mission is to help people be clever with their money. And when we talk clever with their money, we're not just talking consumers, we're talking about merchants as well. Carolyn and the team are at the forefront of of real time payments. And as you'll hear from Carolyn today, real time payments have gone from just being introduced a few years ago to now representing almost 10% of payments around the world. Carolyn found that there was a huge untapped opportunity in C to B real time payments and that's how hello Clever came to be. But what's most interesting is that this isn't just a payments company. This is set up as a customer acquisition and growth company as well as a payments company to save you time and to make sure you get paid in real time through hello Clever. Merchants can offer cash back to customers and most merchants are doing this using the fees that they would save from other payment methods. It's a really interesting concept mixing both payments and loyalty together. Today, Carolyn gives us a quick fire lesson on what real time payments are and the opportunity with real time payments, how she has set up hello Clever to help both merchants and customers be clever with their money and gives us some tales around how she actually got into the world of finance when she was in the world of media beforehand. And she seems to handle it so simply. Thanks to Shopify and Klaviyo. Here's my conversation with Caroline Tran from from hello Clever. Caroline, welcome to ADD to cart.
Caroline Tran: Thank you so much for having me Nathan, super nice to be here.
Nathan Bush: Super great to have you here now. Hello Clever. It has to be a name that stands out in the finance sector. Right? So I can't think of any other financial company with a name as fun as hello Clever. Do you find that you stand out?
Caroline Tran: It actually is. And I do have a lot of people every single day ask me about, how do you come up with a name, where's all skits done, you know, started? And I had to be like, you know, being there and tell them the story. So. But it's really click. I mean, thank you so much for saying that. And yeah, we started the business because we just want people to be clever with their money. And that's why the reason of the name.
Nathan Bush: Are you clever with your money?
Caroline Tran: I am. You know why? Because I'm an accountant. It has to be like, you know, a financial, personal finances or everything I care for. So yeah, has to be.
Nathan Bush: All right, well, let's get into the story because I've been following you for quite a while. You are this amazing Australian tech finance story that I've been following you and you've had your raises along the way, team expansion, global expansion. And I've just been like, we've gotta have a chat. But there's also been a part of me that's like, I just can't work it out fully because you do so much. Right, so there's the real time payments piece, there's the shop back piece, there's the payments piece, there's a lot there. Can you tell us what, what does hello Clever do?
Caroline Tran: Yes. So in a few sentences, hello Clever, we are a global payment company that combines instant cash back, embedded loyalty and intelligent insight into one place. So when we started hello Clever, the only product that was launched in the market was a B2B 2C Payment gateway products which leverages the, you know, real time payment platform in Australia, which is npp. I'm not sure you're familiar with new new payment platform.
Nathan Bush: So NPP enough to be dangerous?
Caroline Tran: Yeah, exactly. It's in 2021 when NPP was like taking off, you know, where people in lockdown and thought digital payments was emerging.
Nathan Bush: What does NPP stand for?
Caroline Tran: New payment platform. It's really simple.
Nathan Bush: That's very simple. That's not what I expecting at all.
Caroline Tran: Yeah, literally RBA decided to call it npp. So it's really easy to understand. Right? It's literally payment platform.
Nathan Bush: Okay. And that was introduced in 21, in
Caroline Tran: 2018, but it took off in 2021 because of you know lockdown people was you know really into digital payments because you can't get out, you have to be out, you know, doing payments online and stuff like that. So we were one of the first fintech that plug and play into the new payment platform. But we thought you know okay, this is great. The use case was around peer to peer payments so I can transfer from Caroline bank account to Nathan SP bank accounts, you know via PayID if you familiar with PayID as well. But there isn't a use case around consumer to business. So Carli cannot transfer to our business. Right. We decided to took that advantage of being the first to build out a consumer to business payment. But we realized that people are not familiar with this new payment method then how we're gonna you know, encourage them to use you know, PayID at the checkout. So that's why we're thinking of a way that we can incentivize consumers to check out with with PayID and therefore you know the instant cashback value props was created. So basically when a customer's pay with hello Clever at the checkout you get instant cashback right away and cash back has been proven in the market for years. Cash reward, one of the prominent, you know, cashback platform in Australia has been around for 20 many years and owned by the banks, they got millions of customers. I was a customer before as well. So we thought cashback was a really great value ad for you know, consumers to encourage them to use this new payment platform. And that's why you know we built the Australia first consumer to payment under the new the NPP and PayID.
Nathan Bush: And so you went out to solve that problem. Why had no one else done b2c pay ID before? Why were you the first ones to come in and do it?
Caroline Tran: Yeah, because we started hello Clever already with the consumer app. So we had a consumer app around 10,000 users. So for you to build a C2B or consumer to business payment you have to have consumer value props. And a lot of I guess other fintech companies wouldn't want us to do, you know, a two sided marketplace. Right, Because I think you have to invest in the C and also invest in a B. But for us we already started with the C so it is a no brainer for us to do this. Right. So we was really fortunate to become the first fintech that actually Genzac the NPP on Pay2. So Pay2 is another form of NPP and it is a similar to direct debit but it is real time. So if you're Familiar with the payment world. Direct debit right now is not real time. So for example, if you pay for your gym membership right now, right. To like anytime fitness or anything like. Yeah. The merchant, what receipt in real time pay to allows real time transaction.
Nathan Bush: Okay.
Caroline Tran: To transact that on, on the MPP and it was through a RBA bank account. So it was quite fortunate. So. And I think one of the advantages of PayLockLever is that we build products at speed. So it took us like not weeks, not months, couple of days to do that. Right. So taking advantage of the first mover in the market, I would have to say.
Nathan Bush: So this sounds incredibly complicated to me and it's just because it's not my world. Is it complicated or did you just have to come up with a proposition?
Caroline Tran: So it was complicated to get into. And speaking with the sponsoring bank, if I have to say, because banks in Australia, you know, obviously the Commonwealth, the big four, they are really consumer protection and retail focus banks. Right. So everything about consumers. So we have to go into the ecosystem and demonstrated our use case to allowing this particular use case for the industry to be able to roll it out. Right. And in order before that you have to have, I guess, licensing robust compliance process. You have to demonstrate you have a risk and mitigation as well process to make sure that there is, you know, minimal in frauds and scams. Right. Because you're going to think about protecting the consumer first. So. And therefore, you know, for a startup of, you know, just starting, you have to invest into getting, setting up your compliance department and it costs millions of dollars. Right? Yeah. So there is a really, I guess, high barrier to entry. If you wanted to start a business like us again, there is the, I guess, opportunity for you to enter it. But it would take time to do it because of these requirement and regulations, risk and stuff like that. Yeah.
Nathan Bush: As a startup, how did you get over those barriers?
Caroline Tran: Okay, so this is, you know, getting back to it. So I have to cold call a lot of chief compliance officers. Like literally I went on LinkedIn and DM, every single chief risk and compliance officer like me or Melbourne, because we, we had no experience back then. Right. So I was fortunate to be able to speak with like three or four of them. And they gave me really good advice. And from them we just obviously, you know, speak to a few lawyers around the processes as well. And then yeah, we were really fortunate to find an advisor who were in the industry for 20 years and be able to guide us through the whole process. And ever since, you know, We've been able to build our own compliance department. And obviously on top of that, we did raise our seed rounds, which we announced in August 2022, of four and a half million. So obviously part of it was to build out the initial team member of our compliance department.
Nathan Bush: Yeah, amazing. And taking it forward to where we are today. How do you summarize where you're at in terms of growth, how many markets you're in? Give us a sense of the scale, of course.
Caroline Tran: So when we started we were thinking Australia, obviously this is home and we wanted to create something really meaningful for the consumers and the merchants and the SMEs in general to leverage real time payment because it's such a great product and it has been invested billions by the banks. Right. So, so there has been a lot of obviously you know, growth during the process. But then we since realized merchants don't just sell in Australia. Right. They sell globally. So that's why back in, you know, late last year, we have to then redefine our roadmap and want it to be, well, I wanted to serve global merchants, I want to serve Australian merchants as well, but sell globally. So that's why we've been busy the past four months to build new products. So merchants can live in 20 markets. So as today merchants can go into hello clever. Create a merchant account with one single integration. You don't have to integrate like multiple times to get into 20 markets. Because the fact is that some auto payment companies, if you are a merchant, global merchant, you have to go through the API or the tech stack to integrate every single time in each different markets. We simplify the whole process and make sure you can grow global from day one, which is really phenomenal. Right. For the merchants who, you know, sells globally. So it works really well with like travel agencies and merchants that do global, you know, ticketings and stuff like that. So, and then we can help merchants settle their funds locally as well. So what it means is that if you're an Australian merchant that's selling in the US we can settle, we can collect in the US and settle into your Australian bank account. Instead of asking, you need to be settled in the U.S. something like that. So create a really seamless global payment solution. But merchants come to us not just because of global payments, right. They can go to stripe, they can go to any other big payment giant companies like PayPal, etc. So the key differentiations between hello clever and these players is that we enable growth under the payment staff as well through loyalty. So whether it's Instant cashback or a seamless API that you can design your loyalty flow. So basically replace discounts. Right. So cash back, replace discount, optimize, you know, your payment under our payment stack. So you can not just save money on the payment processing costs because merchants are paying 3 to 4% at the moment. Right. So for us it is a fair price but a premium service at the same time enabling, I guess, top line revenue for them as well. So it is a win win. Right. So and then recently we launched Clever AI product which is a, you know, AI multi agent AI which, you know, monitors and how you proactive insights to what happened to your business so you can make decisions in real time, not waiting for, you know, hours a day to, to know what's going on. Right. So we turn women into a growth engine and for you to do this, you need to build payment from scratch and as I mentioned, compliance, regulation, risk and all of that. Yeah.
Nathan Bush: And you've just done that, you just rebuilt payment from scratch. No biggie.
Caroline Tran: So we, we did, we did the entire foundation. So it took us like obviously a year or more, two years to that foundation and then you know, now adding more and more values to the merchant. So if I get Cashback platform wanted to do something like what we do, they have to become a payment company, right?
Nathan Bush: Yeah, yeah.
Caroline Tran: They're not. Right. So they're more affiliate. So yeah.
Nathan Bush: All right, I want to come back to the loyalty and the cashback and the AI. But first I just want to make sure that I'm getting the payments piece. Right. You've introduced a lot of concepts so quickly for me. My brain takes a bit to catch up. So if we're talking payments, obviously the benefit for merchants is that they're getting the payment in real time.
Caroline Tran: Yes. So merchant receives the capital when the customers pay under. Hello Clover. The merchant receives that in their bank account in real time.
Nathan Bush: Yeah. And customers not paying any credit card fees or additional on top.
Caroline Tran: Exactly. So you don't pay anything but you get cash back even. Right, yeah, that's.
Nathan Bush: And then how it's shown in the checkout. So if we're just thinking from an e commerce perspective, then if I'm going to shop at. Who's your biggest merchants? Give us some merchants.
Caroline Tran: So Aftershock, which is one of the largest commuter store in Australia. Yeah.
Nathan Bush: So if I'm going onto the Aftershock site and getting all the way through to checkout and then I'm getting to payment options. Are they a Shopify store?
Caroline Tran: They are Shopify plus store. Yeah.
Nathan Bush: Okay, so if we're getting to checkout, you obviously got Shopify Pay there as an option. You open up more payment methods. Is hello clever one of the payment options or is it just labeled as real time payment or direct debit?
Caroline Tran: So we make it flexible for merchants to decide. So we are at the moment on Aftershock. We are one of the payment options. So you would say pay with pay ID powered by hello Plumber. Right, gotcha. And then pay with PayID. You get 5% cash back, right? Yes, but we are doing that where shop pay, there'll be like one click checkout shop pay after pay, obviously buy an hour per later. So you can see the difference between. So aftershock, as soon as I buy a computer, you know, like one of the PC, custom built PC, it costs you that.
Nathan Bush: Yeah. They're crazy. Those, those PCs, they're mental.
Caroline Tran: $100 back, like literally so good. Right. As a consumer, honestly, we run campaigns like that for after shop and like Cashback went crazy, literally. So we make it flexible for merchants to invest into this because it's similar to how you invest into a marketing campaign. Right. So you run use on, you know, during, I guess, weekends. Right. For two hours. Cash back 10% normally for someone like Aftershock, because the ticket item is really, really huge, like 2000 average, but I do about 3% and you get, you know, $6 back. Right. Immediately.
Nathan Bush: So similar to the afterpay model where they can run promotions with their group, except instead of going into debt, you're getting cash back straight away.
Caroline Tran: Yeah, yeah, yeah. So we don't encourage credit transaction, we're encouraging debit. So basically you getting your money right, you save and. But you get cash back, so you get rewards for spending your money.
Nathan Bush: Amazing. All right, cool. So I've got the payment bits down pat. That all makes perfect sense. Roughly in Australia, where are we sitting in terms of real time payments or this new payment type compared to traditional methods such as credit cards or afterpay.
Caroline Tran: Yeah. So Australia is a market where like, I have to say, like 50% of the consumers are using Apple Pay or digital wallets. Right. And then the rest of them are all about debit card credit cards. So as of, I think last year, so real time payment was sitting about 10%, whereas the buy now pay later sector sitting about 4%.
Nathan Bush: Wow. It's bigger than what I thought.
Caroline Tran: Huge. It's huge. But it's obviously including all of the UKases. So basically peer to peer payments, business to business payment, consumer to business payment.
[Voiceover]: Okay.
Caroline Tran: And I think it's worth like you know, obviously, you know, billions of dollars industry. So so basically it is increasing as you can see probably if you go into Amazon right now they are enabling real time payment already. So they did it last month I think in partnership with nap. So unfortunately it wasn't us. But Amazon is obviously as you know is one of the biggest merchant in Australia. So they did that already. But the difference between what Amazon is doing with us is that I think you get 5% discount when you pay with NPP return payment instead of cash back. Now obviously I would question that because discount versus cash back much like makes such a huge difference. Right. Because we believe and this is what we see with our merchants, cashback is more of gain rather than discount is more of a less loss. Right. And you kind of like devalue the brands a little bit if you're giving discounts. Whereas cashback you can create a post purchase experience as well and there's consumer data that coming into your system that you can do a lot with it instead of just like ah, just a one off discount. I don't know who's this. Right. So yeah, so as you probably know cashback has been around for 20 years. The industry is growing as well. Shopback is a really great place player do about 80 million revenue a year. So that is amazing. Right, so, so that's why we're trying to combine the entire system together and one, you know, stop shop for all what merchants needs. Yeah.
Nathan Bush: And the traditional payment methods, are they trying to squash you? Because I can imagine there's a hell of a lot of revenue to protect there.
Caroline Tran: Yeah, for sure. So what we're trying to do and trying to achieve here is obviously we offer a fair pricing. I have to say it is so much better than the traditional one. So for example PayPal or even debit and credit cards because real time payments is local. Right. NPP is local and it is offered by you know, the local banks. So it is has been obviously removing a lot of layers already because so basically card payments are expensive because you've got so many parties involved, everyone want to cut. Whereas local payment is already introduced by the banks, local banks. So there's no five other parties involved and that's why it is better price for merchants. So that's why if you jump on real time payment right now it save you million of dollars. Right. If your merchants that process 50 million I guarantee you we save you a lot of money. Yeah.
Nathan Bush: Are you speaking to a lot of merchants who don't even Know this is an option. I'm just trying to think why wouldn't you have this as an option?
Caroline Tran: The merchants, so large merchants. Right. When you think about large merchants, I think it's just because of the change management that they have to go through. They will accept this in the next five years, 100% but it's just because still new. So it, there's a lot of change management going through the system and also also the legacy system that you have to deal with for large enterprise merchants. But for merchants like SMEs Mid Market we build order plugin and pre integration already into like the largest e commerce systems. So that's why you're literally just a day job, not even like a couple of hours where you can plug and play into our payment gateway.
Nathan Bush: You make finance sound so easy.
Caroline Tran: Yeah, no, because you know it a way for us to make sure that you know, the merchants understand the benefits of real time payment. You get your money now instead of like waiting for three to five days. So stripe will settle your collections in like three to five days. Right. Whereas for us we settle instantly. And the good thing about return payment is that I need to mention there is no chargeback. Right. So it saves you a lot of time and effort and money as well.
Nathan Bush: I was literally talking to a retailer yesterday who was just they do a lot of their trade on a Saturday, they're very weekend heavy. And she was just saying coming up to peak, she doesn't get that money back until the Wednesday or the Thursday. And she's like I know it's only four or five days but it makes such a big difference because their stock is essentially fresh stock. So it just makes such a huge difference to her to have that cash available to her immediately.
Caroline Tran: No, definitely, yeah. Have to jump on real time payment for sure. So yeah, so I guess because it's still new, so it's only been around for 2021. Since 2021. You will see the adoption of this in the near future because there's several markets around the world has been proven this model. Right. So for example I have to give you example of Singapore. Like 80% of you know, businesses in Singapore accept real time payments. And then you know Europe as well has been around as well, Brazil and India. So their definitely emerging trends on real time payment on the consumer to business use case. So in Australia it's only been around for three years so it needs time to adopt, you know. But we are fortunate to be one of the first fintechs who really builds that use case and we're just waiting for more moments for the growth to come, you know.
Nathan Bush: Yeah. All right, well I want to talk about that growth engine being cashback and loyalty when you talk cash, cash back. So let's take that example that you had before. I go through, I buy a PC, I'm getting $300 back on my PC. Who's funding that cash back?
Caroline Tran: The merchant will fund that cash back. So in hello Clever Merchant Dashboard, there is a tool, it is called cashback Campaign. What I will do is that we will let the merchants to flexibly set up a cashback campaign. Depends on their budget. Right. So if you think about all the cashback platforms like Shopback or Cash Rewards, you have to go through another affiliate platform and it fix cashback. Right. We are dynamic. You can set up, let's say during pick time you give, you know, 3% and during like quiet time you give 5%. So it's super dynamic and it fit into your budget as well. So let's say I have $5,000 budget because it's coming out of your marketing budget. Let's run it during the quiet time. Right. And give them the most cash back or whatever you wanted to design it. So there's a product under our merchant dashboard, it's Cashback Campaign. Now we launch another product. It's called MyStone Campaign under hello Clever. So what it means is that you're going to rewards your regular. So every single time. So it's like what we visualize it as a digital coffee card. So you come back and purchase a PC, you know, I don't know like once a year or whatever you rewards further or it wouldn't apply for PC because you wouldn't do you come back
Nathan Bush: for parts and accessories?
Caroline Tran: Yeah, accessories and you know, clothing, fashion, apparel. So I come back and purchase and I get, you know, rewards even more and it's all embedded into payments. Right. You cannot do this without a payment system. We give the customers cash direct.
Nathan Bush: And do you find that your merchants are advertising that cashback option further up in the journey or is it usually waiting until they get through to checkout to surface that
[Voiceover]: decuber's mission is to leave the world more amazing than we found it. So what does that look like? It means prioritizing sustainable practices, empowering amazing, amazing people and sending less rubbish emails. With the help of Klaviyo, Decuba have been able to do exactly that and achieve 34% growth in revenue from Klaviyo Flows. With Klaviyo, Decuba has been able to confidently send More emails knowing that they will be valuable by responding to omnichannel behaviors and targeting at risk and high intent shoppers differently and growing lookalike audiences. See the world doesn't need less email, just needs amazing email. To explore how Klaviyo can grow your e commerce business and to see more case studies like this, visit klaviyo.com au.
Caroline Tran: Yeah, so they would normally if they run a campaign like that, they will advertise it in their their edms or on their website. Right. During. In a financial year, you know we do cash back during this time and this time. Right. Get quick and to be honest some of the campaigns run out like literally 15 minutes. It's crazy minutes is right at $5,000 like and so it means is that customers actually going to wait for that moment to purchase and it's increase the revenue for the merchants at that point.
Nathan Bush: And they're justifying this cash back are they? By reduced fees?
Caroline Tran: Yeah, yeah.
Nathan Bush: Okay. So that's the calculation you've got to do to understand that if I can shift customers to spend more, buy more and use real time payments via hello Clever I can actually justify giving away this much cash back because I'm not losing in other fees.
Caroline Tran: Yeah. So basically because you have been saving that much of payment fees, you're using our payment fees savings to become a cashback. Right. And then it help you to increase your revenue. It's literally a no brainer for it makes sense. Yeah.
Nathan Bush: Tell me some of the most, what are some of the most creative examples that you've seen of integrating all this together?
Caroline Tran: So we work with merchants in especially you know, travel sector and so travel sector to be honest is quite high risk because what if Covid happens again? Right. So people cannot travel. So there are a few, you know, campaigns that we are launching with one of the I guess largest booking system in Asia Pacific. It's called Travel Loca. I'm not sure if you know them. So, so we've been running a few campaigns with them and you know we see how you know, payment has saved them a lot of fees. Right. Because they are a global business. So they, they sell tickets in like 50 countries and you can imagine how you can do all of a payment integration in each of every single country if you go through hello Clover. We can just do that to you. Right. Literally.
Nathan Bush: Gotcha.
Caroline Tran: So it save a lot of technical efforts as well as you know, we can centralize everything in one place. So you are as a payment manager or like a financial manager, you can just Go into our payment dashboard and have a look at which country you've gone live and who has been paying and buying which tickets. Right. So it has been a really interesting use case for us. So we do find a lot of traction in high ticket items, for example computer stores, furnitures and then travel sector. Right, okay. Wholesale, globally. Yeah.
Nathan Bush: On those high ticket items. So do you find then that there's a segment of customer who is continually shopping for hello, clever cashback. So if you think back to how afterpay launched in the market, it was all about the Afterpay directory. In that afterpay essentially put pressure on a whole bunch of retailers to say, actually we've got all your customers reaching out to us saying, I wish brand A, B and C was using afterpay, otherwise I'd shop there. But I'm not shopping there because I'm shopping with the shoe brand that's offering afterpay because that's how I like to shop. Now are you getting that same kind of pressure from your customers?
Caroline Tran: Yeah, in terms of the consumer side, we do have like customers reach out to us like because of the cash. So basically there's some, you know, instances where customers reach out to us and be like, hang on, I don't get my cash back. What's going on? And then we have to come back to the merchants and check with them. Oh, actually the campaign has been finishing like, you know, literally at the last minute of the campaign. So sorry, your dance session wasn't part of that campaign. So people get like upset about it because they were just like, hang on, I was here because I wanted to, you know, buy this item and I get cash back instantly. Right. So we see a lot of emerging use cases like that, which is really exciting and it's proven our model. Right. And sticking to our vision. We want people to be close level of their money and we want rewards for their, you know, purchasing behaviors. Like because a lot of transaction through our system is debit transaction, what it means is that it is your money. You want us to purchase this item or purchase this holiday because you obviously deserve it, so you're getting rewards for it as well.
Nathan Bush: I really like your marketing around being clever with your buddy, like coming from a payments company to say we're here to help you be clever with your money. What kind of cut through have you had? Especially I suppose I'm interested in those younger generations, the Gen Zs. What kind of feedback are you getting from younger shoppers?
Caroline Tran: So they love instant replication. So, you know, there's a Lot of products that have been giving Gen Z the instant verification and we thought rewards hasn't been instant verification at all, you know, the past 20 years. So we wanted to change that. And we cannot change that without building payment first. And that's why we took the advantage of, you know, the whole world is building real time payments right now. Right. So there has to be a use case for instant rewards, paying your cash back instantly into your bank accounts. Right. So otherwise, you know, we were thinking about how we can make rewards instantly without payment. You cannot unless you pre fund that cash back, which is a risk. And as a business, a startup, you cannot risk that. Right. So it has to make sense. Sense and product has to make sense. And that's why, you know, we thought, you know, become a payment company is the start and that is now our moat because we now plug and play into like 30 banks across the world. Right. So we have that moat. If you want to speed that, you need license, you need compliance. We are licensed in Australia and we're looking to get licensed in, you know, the rest of the world. And I'm sure they have more use cases as we go.
Nathan Bush: Yeah, yeah. What's the next global expansion? Where would you like to play?
Caroline Tran: So interestingly, recently we opened our entity and operation in Japan. It has become a really interesting market for us. As you probably know, Japanese is really risk averse, like risk averse. And it took me like I think six months to a year to just create an entity in Japan. It's crazy. So recently we, and I cannot announce this yet, but Japan has been a really good market for us and we're looking into the US right now because FedNow, which is an equivalent payment system to NPP in Australia, launched last year. So they launched that product last year. We need to take that advantage of, you know, being one of the first, we cannot miss the boat. So we, we're looking to launch in the US really really soon and merchant in Australia. I can just use real time payment in the US like literally now, today I can turn it on.
Nathan Bush: That's cool. I'm keen to understand from you as an entrepreneur, first Mover Advantage, obviously you've jumped on this really quickly and you've got that advantage. Are there times where first mover advantage has also kicked you in the butt?
Caroline Tran: Yeah, there is. So I'll give you my better example. Obviously if we are too new, we need to spend our resources to educate the market. So if you go on YouTube right now and search for how to pay with PayID, it probably hello. Clever is the first video, right. No one has done it and we did our first video to educate a consumer how to pay with PayID and it got like thousands of views on that video. So yeah, so one of the cases where you know, it's too new, everything is like new. It takes time to educate consumers, take time to educate merchants. But I think it's also a good way because then you know we going to have to create a legacy and this is something that we're quite proud of to be first mover in Australia and continue to be a product that keep innovating industry. Right. Because for example AI. Right. What we can do with AI in payments and stuff like that.
Nathan Bush: Yeah, and tell me about that, that AI release and the insights that you're gathering there because I'm really keen that you would get so much data through there. There's so much compliance, there's so much risk, so many directions you can go with AI. Where did you start? Where are you putting most of your efforts?
Caroline Tran: Yeah, so we started you know, bidding out a use cases for AI late last year because we thought, you know, so basically my co founder Gavin, so he studied AI and machine learning in RMIT Melbourne like three years ago. So he's a BHD candidates now at rmit and I thought, you know Gavin, you're an expert in this, right? What are we waiting for? So immediately we built out our AI team. So our AI team right now at hello Clever is consisted of the three PhDs including Gavin in first of all his major is in visualization. So basically how it can detect an image and translate into a business context. And Gavin's expertise is in hallucination like need to make sure AI like doesn't hallucination at all. And Henry hits major races in time series forecasting so how can utilize data to forecast the future. So sort of tense it out together and build our clever AI. Basically it is a clever data analyst to make sure that it monitors give you productive insights to help you to make business decisions in real time. Right. So you are right. So payment data come to us every second pre process millions of transactions. Right. So we wanted to make sure these insights come into actual insights for businesses. So we launched three products. It's called Clever AI Forecaster. So we help you to forecast your sales and revenue. We help you to forecast our cashback campaign. For example, if you invest $10,000 into a cashback campaign, what kind of return you can get and get generated to make sure there is a visualization and guarantees of results and I guess a play of confidence, right, for you as a merchant, if you invest into it. And then there is clever AI data analyst as a chatbot. So we are launching a chatbot. It's similar to TBT style but it is based on our data. So the difference between that is it's real time data fitting through our system. So for example Caroline, purchasing something literally right now as we speak, I would give you that data, right? Whereas GPT, you have to upload the data and it probably takes to analyze because it fits through our system. So we would be prompted right away for the merchants and a couple of others that in the roadmap, for example, you know, we're forecasting your sales. We want to forecast a bunch of other things such as inventory levels, you know, customer segment analysis and a bunch of that. So it's really crucial for a business to understand it. Right. So we want to place a business analyst in your company and just use clever AI to do a couple of things and it is part of that payment transaction anyway, you know, so it's create more stickiness for emergency users.
Nathan Bush: That's cool. You mentioned before around one of the challenges that you have in establishing yourself is that or what the reason no one else has gone down that path is because you actually need to be a marketplace. You need to bring, you have need to have your consumers together and you need to have your businesses. And we've seen with payment options like Shop Pay for example, they've been able to infiltrate a lot of businesses and through Shopify be able to power many, but then also then bring it into one app where customers can be recommended products in a really smart way based on what they've purchased. Is there any way that you're thinking about taking the relationship between all your merchants and helping your merchants cross sell with each other based on the data that you've got?
Caroline Tran: That's really interesting suggestions. We haven't thought about that Nathan, but maybe for me in the roadmap we give the control to the merchants themselves, right? So we super merchant focus, like whatever you need. We're going to build your our products surrounding your growth. So obviously starting from payment and then you know, embed into loyalty with cash back and then now data, right? So there's a lot of things that we potentially could do together because we do not monetize on a consumer side, we monetize on the emergency side, as you probably know. So you know, companies like yeah, shop, PayPal, Afterpay, they monetize on the consumer side as well. We don't yet because at the moment the majority of our consumers are still in Australia. But we do look for opportunities to grow in the US soon and then Japan. So we pick markets that we think consumers loves cash back. Right. So for example, obviously emerging markets like Southeast Asia, Africa, they love that as well. But it's just the amount of unbanked, you know, consumers in these market is quite large. So there has to be different strategies. So we do love to build, you know, an ecosystem where merchants can communicate with each other and you know, obviously monetize and make sure there's, there's growth platform for them as well. But definitely that would be something interesting for us to consider.
Nathan Bush: Yeah. Is it difficult when you're entering new markets because you've got multiple messages to land on the consumer side? So obviously less payment fees because you're going direct, but then also you've got your cash back. How do you balance the two? And over the top of all of that, you've got the education piece as well. I can imagine there's a lot that you need to land straight away.
Caroline Tran: Yeah, 100%. So we started with merchant first, always. Right. So I guess 90% of our focus right now is on the merchant side. So if we wanted to start in a new market, we have to again starting from building a payment rail or payment infrastructure from scratch. Scratch. Right. So it's not like literally just go in there and block and play with stripe. It's not going to work like that. So we have to go through several steps to be able to build out a payment rail and then build out, you know, your cashback value props, your clever AI value props. Obviously it is one global, but in order to do that you need a payment rail. So entering the US for example. Right. We had to be then, you know, obviously hire a local lawyer, hire a local director to guide us through the whole process to plug and play into the bank. Right. So it's getting done now. It probably takes us again. You know, I think I started the conversation earlier this year and we only just get the final, final stage, so it takes a while to do that and then I have to then invest into engineering resources to build that out. Right. So it probably takes another two months after, after we get approved and I
Nathan Bush: bet it's such a slow process to get all those approvals done. And then as soon as it's done, you've got to move ultra fast.
Caroline Tran: Yeah, ultra fast to get it done and you're going to sell it to the merchants and then during that process you're going to maintain it as well. So it's not just about get in and then you're done. Right. You have to maintain the relationship with your bank. Otherwise, you know, what if you know you, you do not have a proper process? What if there's a merchant who is the scam? Right. So you have to make sure there is the end to end process to follow and no, but it's create a lot of, you know, exciting times for us to expand, explore into new markets. Right. We found consumers in the US is quite similar to Australia, Japan also surprisingly also quite similar. Everyone love Cashback, right. So you see that is a really good hook for us to start and then. Yeah. And then obviously, you know, with a lot of data coming to us, there's a bunch of things that we're doing in the background.
[Voiceover]: Shopify is committed to keeping their merchants
Nathan Bush: at the cutting edge of innovation.
[Voiceover]: And the features released in their Summer 25 edition are no different as they give brands the tools that they need to work smarter today and thrive in the future. For example, Shopify's AI tool Sidekick just got a lot smarter. It's able to synthesize data from multiple sources simultaneously. Moving beyond basic Q and A to solve complex business challenges, they've also made sense scaling globally even easier. With Shopify payments you can now manage various business entities and settle up in multiple currencies from a single store. And for instore POS has been redesigned making the day to day experience for retail staff easier with improved search, intuitive navigation and a more flexible card. Check out over 150 features that have been released by searching Shopify Summer 2025 Edition.
Nathan Bush: I was just thinking around risk for your model. What are the biggest risks that are there? Because I can imagine obviously a newish payment model with real time payments plus cash back into bank accounts. What are the biggest risks that you have to manage?
Caroline Tran: So the rest is from fraudulent activities, you know, obviously scams. Right. So for example, you're being attacked by a group of consumers who purchasing something online and then yes. So you pay with return payment. The merchant receive the money right away. But then they will call their bank and said I didn't buy this, I didn't, you know, I didn't do this. And the bank would then come back to us and be like what's going on? Right. Because the bank is always protect consumers and we love that. So there has to be balance and really I guess prepare process to make sure that both merchants and consumers are protected. Right. And that is one of the key challenges in payment industry as a whole anyway. Or for example, if, you know, maybe, you know, at the moment, crypto currency is really popular. There's a lot of frauds around that as well. So we need to make sure that we don't accept merchants in crypto industry. But we do have a lot of merchants that come to us and be like, oh, can you. Onboard cryptocurrency platforms, et cetera. We said no to them right away. So you need to kind of identify the kind of merchants you want to work with as well in that way. Yeah.
Nathan Bush: How does it work in terms of returns and refunds? So if you're giving cash back straight into a bank accounts post purchase and then customers go, actually I'll have a refund. How do you get the cash back? Back?
Caroline Tran: Yeah, so good question. So because we are a payment company, we can just give them refunds right away, instant refund, but minus the cash back that your husband fair and swear. So it's in our commercial contract because the consumer will have to accept TNCs and you know, then they make sure they give consent on that and on the merchant side as well. So everything. So as of today in Australia actually we are the only fintech that offer automated return for merchants. So you are on real time payment at the moment. Everything is so manual. So the banks will send it to the payment company in an Excel file. Believe it or not, that's a big
Nathan Bush: selling point in itself. We've had startups launch in Australia purely with that one proposition.
Caroline Tran: Yeah, exactly. No, we do everything automatically. So we build that ourselves. And I can show you that you can speak to anyone in real time payment industry. So every single time if customers complain, the bank will send an Excel file to that payment company and then that payment company will send an email manually to the merchant and asking why we automate the whole thing. So the merchant literally just go into dashboard, we will send that notification to the merchant automatically and they just upload. It's similar to what Stripes run, but we did that for real time payment. So yeah, it's funny because I just realized that now. Yeah, yeah, we did the entire things automatically for merchants.
Nathan Bush: That's very cool. Caroline. What really strikes me is that you are in this brand new world and in a really complicated part of E commerce. And I know it's broader than E commerce, but what you do is complicated and it's global and there's a lot of legal coming to high regulated industry. Exactly. High fraud. There is so much risk involved, so much growth. But you manage to explain Things so simply and so clearly for people. How do you maintain that level of balance in a world that I can imagine you must have a thousand things on your plate at the moment or a thousand thoughts of what, what's going on everywhere. How do you maintain the balance?
Caroline Tran: Yeah. So basically, you know, there's a lot of things going on here. Right. I think it's coming from, you know, my background. So I wasn't in payment industry. I literally was in media before this. Like we organized the Masinga and a bunch of that, you know, those shows and I decided to quit my job and we just stumbled up, you know, appoint payments and we thought it's really interesting no one solving his problem before. So. So I think because of that we come from a really fresh perspective so we can I guess explain to our audiences with a really simple terms. Right. Because otherwise no one can understand what we are doing. Yeah. France, where we do real time payment, we give you instant cash back, we give you real time insights. Done. Right. And it's at fair price, not at like you know, the price that you cannot afford. So it is a win win for you as a merchant. So I guess as well as you know, you need to have a team who are expert at payment as well. So not like oh, we, we don't have an appointment experience and then the rest of the team don't have payment experience. That's going to take us time to learn and adapt. Right. So we do have a team who's obviously expert in the industry as well to get us move faster. Right. To get us to the right direction. Right. To get us to speak so the right people in terms of regulation. So and obviously for me as a co founder and CEO, it's all about how I create a vision and how I'm going to lead with the vibe because people need to have fun along the journey as well. That's what I believe. So and coming from media industry, I think it was really fun during my time in media and I thought, you know, why, why don't we just create a fun tech, you know, in.
Nathan Bush: Yeah, why don't I just start a global payments company?
Caroline Tran: Yeah, yeah, why don't we just do a global payment company? Actually we started in Australia first but yeah, let's go global tomorrow. So that's what we did.
Nathan Bush: I love it. All right. And surely I'm going to pick your brains here. Surely you've done one dumb thing with money in your life.
Caroline Tran: What is it so invested in stocks that not doing well, I think like before. Hello, Clover I spent all my savings in a company that I shouldn't have done it and they went bankrupt. So I listened to, I listened some, to some people, you know, that FOMO was crazy. And then actually I didn't lose money, but it just wasn't a wise investment at all. So that's what I did. So right now I do also invest into startups which I find really exciting because I've been doing this right. So I know how hard it is to do it and I know how kind of like understand now how to decide which one to invest, right. So. So it's not a lot of money, just like a couple of thousand dollars. But want to get in there, support the founders as much as possible because I know I am the founder and I know the journey of, you know, building a startup is super painful. Right. You're spending 247 to make sure the system still works. So especially in payment. Right. You don't want downtime at all. So that's why, yeah, really like to support like emerging and innovative technologies around the world.
Nathan Bush: Oh good. Found anything interesting that we should share with our listeners?
Caroline Tran: Yeah, yeah, yeah. In obviously open AI?
Nathan Bush: No, I think I haven't heard about them and I don't think they're doing that.
Caroline Tran: Who's open AI? Look, I looked at a lot of companies at Y Combinators and Start May. I think there's a lot of potentials there. So always look out for opportunities. I haven't actually recently invested in like any companies at all because we've been spending a lot of efforts on hello Clever. But if I know anyone, I'll definitely reach out. Obviously lovable, right? You have about local but love support Australian startups. There's a lot out there.
Nathan Bush: That's awesome. So good. What does the next 12 months look like for you at hello Clever? What are your priorities?
Caroline Tran: So our priorities right now is to double down on ARR every month. Oh my God. If we can do that would be awesome. So obviously, you know, keep growing the revenue but one of the things that we really wanted to achieve is that getting our Singapore license and Japanese license, that would be awesome because that is our mope. Right? Three more mo for hello Clever. And then establishing our presence in the U.S. it's really exciting. We have our country lead in the US starting literally in two weeks.
Nathan Bush: Awesome.
Caroline Tran: I really look forward to catching up with the team in New York and then obviously, you know, create more products, innovative products. No one has done it before. We're going to be the first. We have to always be the first, because First Mover Advantage has been giving us a lot of opportunities and we think when I continue to do our research what we can do better, you know who we're going to replace and dominate that.
Nathan Bush: Yeah, that's awesome. Let's just leave it there. Dominate that. Like that's a beautiful ending to our conversation. Thank you so much, Caroline. I just think it's so fascinating what you're doing at hello Clever. Not only did you give us a good little update, a good little lesson on the opportunity for real time payments, but also thinking about how hello Clever can play into loyalty and marketing to grow sales as well as save money. I think it's a really interesting proposition. So thank you so much for sharing that with us today.
Caroline Tran: Colin, thanks so much for having me.
Nathan Bush: I think you'll agree that was 45 minutes pretty well spent if you came out of that understanding more about real time payments and what you knew going in. I certainly did. So I hope that was valuable for you. I think it's a really, really interesting business model that Caroline and the team have there at hello Clever. I've never seen someone, not since afterpay, but afterpay did it a bit differently. Combine payments and loyalty together. All right, there are three lessons that I want to share with you from that conversation. Number one, real time payments. The opportunity around real time payments now representing 10% of global payments payments, obviously a lot more in the B2B world, but growing in that C2B world as well. I think if you do not have real time payments as an option in your checkout, you're missing out not just from a margin perspective, but also from a customer preference perspective. It's really important to have a look at what you're offering and see if that is an additional payment method that you want to offer. Whether it's with hello Clever or another provider, but customers are starting to expect it. As Caroline said, it's not overly complicated to implement. It will take some change management and if you're on an older tech stack may come with some complications, but if you're on a standard tech stack, it should be a pretty straightforward thing to implement. The second thing there was, I love that point when Caroline said that when she felt out of her depths on the legal ramifications around payments, she didn't go and try and sort it out herself. She went to LinkedIn and she found the best people in Melbourne and reached out to them cold and asked for help. In the end she found one of her advisors that way. I think that's a really great lesson whenever we come to a roadblock is not just a plow through and try and work it out ourselves. Go find the people that actually have done it before and can give you the shortcuts. She did this masterfully. And number three, First Mover Advantage. I know there are two schools of camps on this. Some people love being First Mover Advantage. Some people love to be fast followers. Caroline has shown with hello Clever the advantage of getting in there first because she's built a marketplace and a moat around that First Mover Advantage because she was able to demonstrate the value on both sides of that marketplace really quickly. You can see there in a world of packages, payments and finance that typically moves pretty slowly, Caroline knows exactly when to hit the gas and when to get that momentum. And I think that's really helped with her First Mover Advantage. If you enjoyed today's episode, please share it with a friend or perhaps share it with another merchant who you think could use a little bit of real time payments upskilling. And if you haven't already, hit that subscribe button in your favorite podcast player. So we can keep bringing you stories and tips to help you grow in E commerce. If you haven't already. We have an amazing community of over 500 e commerce professionals. It's a learning community. It's free. Come and join us. Head on over to community add to cart.com join us there and continue the conversation. See you next time.
[Voiceover]: Thanks again for listening. And until next time, keep those customers adding to Cart.